Sunday, 21 April 2019


Monday, 18 March 2019
On November 1, 2015, Norwood borrows $430,000 cash from a bank by signing a five-year installment note bearing 5% interest. The note requires equal total payments each year on October 31. (Table B.1, Table B.2, Table B.3, and Table B.4) (Use appropriate factor(s) from the tables provided.) Required: 1. Complete the below table to calculate the total amount of each installment payment.
| Required: | |
| 1. |
Complete the below table to calculate the total amount of each installment payment.
 |

| Prepare the journal entries in which Norwood records the following: | |
| (a) |
Accrued interest as of December 31, 2015 (the end of its annual reporting period).
 |
1.
2.
3.
Here| Note balance | $ | 430,000 | |
| Number of periods | 5 | ||
| Interest rate | 5 | % | |
| Value from Table B.3 | 4.3295 | ||
| Payment ($430,000 / 4.3295) | $ | 99,319 | |
2.
| Beginning Balance = Prior Ending Balance |
| Debit Interest expense = 5% × Beginning Balance |
| Debit Notes Payable = Credit Cash – Debit Interest expense |
| Credit Cash = Computed |
| Ending Balance = Beginning Balance – Debit Notes Payable |
3.
| Dec. 31: Accrued interest on the installment note payable ($21,500 × 2/12) = $3,583 |
| Oct. 31: Record first payment on installment note (interest expense = $21,500 – $3,583) = $17,917 |
Legacy issues $740,000 of 7.5%, four-year bonds dated January 1, 2015, that pay interest semiannually on June 30 and December 31. They are issued at $680,186 and their market rate is 10% at the issue date.
Legacy issues $740,000 of 7.5%, four-year bonds dated January 1, 2015, that pay interest semiannually on June 30 and December 31. They are issued at $680,186 and their market rate is 10% at the issue date.
Prepare the January 1, 2015, journal entry to record the bonds' issuance.

Determine the total bond interest expense to be recognized over the bonds' life.

Prepare a straight-line amortization table for the bonds' first two years.
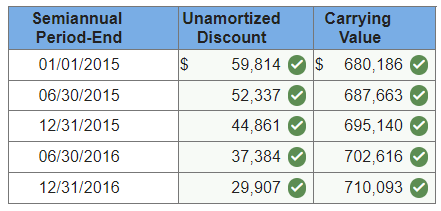
Prepare the journal entries to record the first two interest payments

here
Prepare the January 1, 2015, journal entry to record the bonds' issuance.

Determine the total bond interest expense to be recognized over the bonds' life.

| Eight payments of $27,750* | $ | 222,000 |
| Par value at maturity | 740,000 | |
| Total repaid | 962,000 | |
| Less amount borrowed | (680,186) | |
| Total bond interest expense | $ | 281,814 |
| *Semiannual interest payment, computed as $740,000 × 0.075 × ½ year = $27,750. |
Prepare a straight-line amortization table for the bonds' first two years.

| Straight-line amortization table ($59,814 / 8 = $7,477) |

here
Hillside issues $2,300,000 of 8%, 15-year bonds dated January 1, 2015, that pay interest semiannually on June 30 and December 31. The bonds are issued at a price of $2,815,190. Required: 1. Prepare the January 1, 2015, journal entry to record the bonds’ issuance.
Hillside issues $2,300,000 of 8%, 15-year bonds dated January 1, 2015, that pay interest semiannually on June 30 and December 31. The bonds are issued at a price of $2,815,190.
|
| Required: | |
| 1. |
Prepare the January 1, 2015, journal entry to record the bonds’ issuance.
|

For each semiannual period, complete the table below to calculate the cash payment.

Complete the below table to calculate the total bond interest expense to be recognized over the bonds' life.

| 5. |
Prepare the journal entries to record the first two interest payments.
 |
| 2(a) | Cash Payment = $2,300,000 × 8% × 6/12 year = $92,000 |
| (b) | Premium = $2,815,190 – $2,300,000 = $515,190 |
| Straight-line premium amortization = $515,190 / 30 semiannual periods | |
| = $17,173 | |
| (c) | Bond interest expense = $92,000 – $17,173 = $74,827 |
3.
| Thirty payments of $92,000 | $ | 2,760,000 |
| Par value at maturity | 2,300,000 | |
| Total repayment | 5,060,000 | |
| Less amount borrowed | (2,815,190) | |
| Total bond interest expense | $ | 2,244,810 |
Wednesday, 6 March 2019
Thursday, 24 January 2019
Wednesday, 16 May 2018
Subscribe to:
Posts (Atom)